


For many Americans, there's a disconnect between what's happening on Wall Street and how they're feeling when it comes to their personal finances.
The markets have remained resilient despite periods of volatility, yet many people nearing retirement are worried about whether their money will last through their golden years. Much of that anxiety stems from inflation, which, for the first time in three years, is now outpacing wages.
That's why retirement planning today shouldn't focus on shrinking expenses, but rather on building a flexible income plan that can absorb higher costs over time.
Most people think they need to replace their full working salary when they retire. That's not necessarily true. It's not just about replacing a paycheck, but about replacing the net income that supports your life today while accounting for some expenses that may go away or change in the future.
Instead of gross salary, start with your current net income. This will help you determine what you truly spend. Add up how much money is coming in each month and compare that to how much is going out. Once you know what your income needs are, you can determine whether your current assets are enough, whether your retirement timeline needs to shift or whether your investment strategy should be adjusted.
I believe one of the most overlooked tools to help combat inflation in retirement is the travel budget. Most retirees spend more on travel during the first part of their retirement and then gradually reduce that spending, whether that's due to health or simply wanting to spend more time around family.
Instead of viewing travel as a temporary expense, think of it as a built-in financial cushion.
An amount as small as 10% can provide flexibility if inflation rises faster than expected. While that money may go toward vacations early in retirement, later on, those same dollars can be reallocated toward healthcare costs or other expenses. Because you know the money is there, the travel budget becomes a buffer to help you feel confident in your plan.
Retirement planning isn't only about how much you have saved in your portfolio. For example, a million dollars may be more than enough for one retiree but not enough for another. Your retirement depends on spending needs, income sources and your unique timeline.
Once you calculate your expected spending and account for guaranteed income sources such as Social Security or pensions, you can then identify the investment gap. Your investment decisions should support your income needs. The strategy should be based on what you need your money to accomplish.
Income planning helps you make retirement decisions based on facts, not fear. Inflation isn't something that you can avoid, but you don't have to let it eat away at your hard-earned savings. Retirees who create room in their plan are often better positioned to handle rising costs, enabling them to live out a fulfilling and financially confident retirement.
Conversations around your finances and estate should never occur separately. At Blue Ridge Wealth Planners, we take the complexity out of financial planning, helping clients create a plan for everything, from investments, income, taxes, healthcare and your legacy.
Disclosures: The information contained herein and any opinions expressed are provided for informational purposes only and should not be construed as a solicitation to buy or sell any security, or as personalized investment, tax, or legal advice. Originally published at https://www.kiplinger.com/retirement/retirement-planning/inflation-proofing-your-retirement.
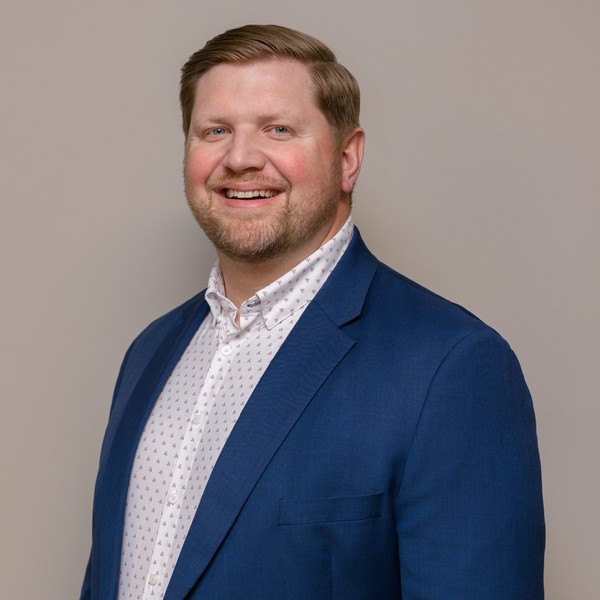
As a former football player at the University of Tennessee under Coach Phillip Fulmer and a high school state champion wrestler, John Vandergriff brings a team-first mindset and disciplined approach to serving clients at Blue Ridge Wealth. After spending five years in ministry and coaching, he joined the firm in 2012 and has since become a trusted advisor and leader, helping individuals and families pursue their financial goals with clarity and confidence.
John is a dually licensed Insurance Agent and Investment Advisor Representative. He holds a Bachelor of Arts in Psychology from the University of Tennessee, combining his understanding of people with a thoughtful, relationship-driven approach to financial planning.
Outside the office, John remains active in his church through teaching and enjoys golfing, exercising, watching sports, and spending time with his wife, Ashley, and their two children.

